Budgeting Tips for College Students: A Practical Guide to Saving and Managing Expenses
Budgeting tips for college students usually come down to three habits: track your income, plan your spending before the month starts, and set aside a small amount for emergencies. Monthly costs for college students typically range from about $700 for students living at home to nearly $1,800 for students living on campus, so the right budget depends heavily on where and how you live.
College often marks the first time anyone manages money without a parent checking the numbers. Rent, food, tuition, and a social life all compete for the same paycheck, and irregular income from part-time jobs or financial aid refunds makes planning harder than it sounds.
This college budgeting guide breaks down how to build a working student budget, what belongs in it, and how to save money each month without cutting out the parts of college that matter most.
Why Budgeting Matters for College Students
A budget is a plan for your money before you spend it, not a record of where it went. Skip that plan, and small purchases add up faster than expected, often leaving rent or tuition underfunded by month’s end.
One national survey found that 45% of college students said financial pressure kept them from consistently covering basic needs like food and housing. That number points to a planning gap, not a spending problem; most of these students never learned a system for tracking money before arriving on campus.
A working budget solves three problems at once:
- It prevents cash shortages before rent or tuition is due.
- It protects your credit score by keeping bill payments on schedule.
- It keeps loan and credit card debt from growing beyond what you actually need.
For most students, money management starts here with a simple plan, not a finance degree. Anyone can build one with a system that fits their real income.
How to Create a College Student Budget Step by Step
Building a student budget plan takes five steps and about an hour of focused work.
1. Calculate Your Total Monthly Income
List every dollar you receive each month:
- Part-time job or work-study pay
- Financial aid refunds, divided across the months they need to cover
- Family support or allowance
- Scholarship stipends
- Freelance or side income
If income changes month to month, budget around your lowest expected amount. Planning for less than you might receive keeps one slow month from throwing off the whole plan.
2. List Your Fixed and Variable Expenses
Fixed expenses stay the same each month, like rent and phone bills. Variable expenses shift, like groceries, gas, and entertainment.
Write down every expense, even ones that feel too small to matter. Most students find at least one forgotten subscription or fee during this step.
3. Set Spending Limits for Each Category
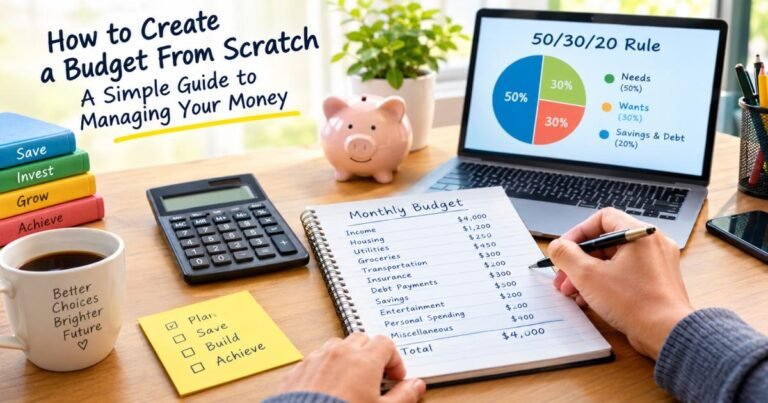
Assign a dollar limit to each expense category once you know your income and costs. The 50/30/20 budget rule offers a simple starting point:
- 50% toward needs like rent, food, and transportation
- 30% toward wants like entertainment and eating out
- 20% toward savings and debt payments
Students on a tighter income often shift this to 70/20/10, and that adjustment is normal. A ratio you can actually hit matters more than following the original formula exactly.
4. Set Aside Money for Savings and Emergencies
Even $20 to $50 a month builds a real cushion over a school year. Automate the transfer on payday; money you never see in your checking account is far more likely to stay saved than “whatever’s left” at month’s end.
5. Track Your Spending and Adjust Your Budget
Check spending against your plan every week, not just at month’s end. A category that runs over three months in a row needs either a higher limit or a specific fix; waiting longer just repeats the same shortfall.
What Should Be Included in a College Student Budget?
So what does a complete college budget actually need to cover? Every recurring cost, not only rent and food.
Housing and Utilities
Rent typically makes up the largest share of a student budget, whether that’s a dorm, an apartment, or a shared house. Add electricity, water, and internet as separate lines whenever they aren’t already bundled into rent.
Food and Groceries
This category covers groceries and dining out combined. College students spend an average of $450 a month on meal plans alone, so comparing that meal plan budget against home-cooked costs often reveals real savings.
Tuition, Fees, and Course Materials
Tuition often arrives as one semester bill, but breaking it into a monthly figure shows its true weight on a budget. Books and supplies alone averaged around $1,370 for a full-time student in the 2024–2025 school year,r a cost that sits outside a school’s published tuition price, so it needs its own line rather than a spot under “miscellaneous.”
Transportation and Parking
Gas, transit passes, rideshare costs, insurance, and campus parking permits all belong here. Students who walk or bike most days should still budget for occasional rideshare or transit costs during bad weather or late nights.
Phone, Internet, and Subscriptions
Phone plans, Wi-Fi, and streaming services often slip by unnoticed because they’re billed automatically. Listing every subscription by name catches costs that would otherwise go untracked.
Personal Care and Clothing
Haircuts, toiletries, laundry, and occasional clothing purchases deserve their own category rather than general spending. A modest monthly allowance here keeps these costs from eating into bigger budget lines.
Entertainment and Social Activities
Movies, concerts, and nights out support your social life, not just your spending habits. Budgeting a set amount for fun lets you enjoy college without guilt or overspending.
Health and Medical Expenses
Insurance premiums, co-pays, prescriptions, and campus health fees all belong in a student budget. Check what your tuition already covers before adding a duplicate line for a service you’re already paying for.
Savings and Emergency Expenses
This category works as a safety net. A small, consistent contribution here does more over a year than one large deposit made once and forgotten.
Budgeting Tips for College Students to Save Money
These habits stretch a student budget further once the basic plan is in place.
Use Student Discounts
Software, streaming, transit, clothing, and food delivery brands often offer discounts exclusively for students. Searching “[brand] student discount” before any purchase takes seconds and can save real money across a semester.
Cook More Meals at Home
Batch cooking on weekends cuts food costs more reliably than any other single habit. Staples like rice, beans, pasta, and frozen vegetables stretch across several meals and cost far less than takeout.
Buy Used or Rent Textbooks
Renting textbooks, buying used copies, or borrowing from classmates cuts this cost well below full retail price. Checking the campus library first: many now hold course texts on reserve- sometimes eliminating the cost.
Use Free Campus Resources
Most colleges include gym access, career counseling, tutoring, and mental health services in tuition and fees already paid. Using these services isn’t a luxury; it’s money already spent that shouldn’t go to waste.
Compare Transportation Options
Walking, biking, or riding a campus shuttle typically costs less than driving and paying for parking. Students who do need a car should compare insurance built for infrequent drivers, since standard policies often overcharge for low mileage.
Review Recurring Subscriptions
A monthly look at your bank statement usually turns up at least one subscription no longer in use. Splitting services like Spotify or Netflix with roommates cuts this cost in half without losing access.
Set a Weekly Spending Limit
Breaking a monthly “wants” budget into a weekly number makes it easier to track in the moment. Managing $40 for the week feels far more concrete than managing $160 for the month.
Avoid Impulse Purchases
One rule filters out most impulse buys: wait 24 hours before any non-essential purchase over $20. If the item still matters the next day, it’s a genuine priority rather than a passing urge.
How to Budget for College Depending on Your Living Situation
Where you live changes what your budget needs to cover.
Students Living on Campus
On-campus students often see total monthly costs near $1,740, largely because housing and meal plans arrive as one bundled bill. That bundling adds predictability, since most major costs stay locked in for the semester and only personal spending needs active management.
Students Living Off Campus
Off-campus students take on separate bills for rent, utilities, and groceries. Even with slightly lower rent than a dorm, total monthly costs often land near $1,660 once every bill is added up; splitting these costs with roommates remains one of the most effective ways to bring that number down. Across every living situation, total monthly costs for college students typically range from about $700 to nearly $1,800 depending on housing choice.
Commuter Students Living at Home
Students commuting from home typically see the lowest monthly costs, often between $700 and $900, since family usually covers rent and food. Daily transportation becomes the main added cost, since gas or transit fares apply five or more days a week.
International Students
International students often carry additional costs like visa fees, international health insurance, and higher tuition tied to non-resident status. Currency exchange swings can also change how far money from home stretches, which makes a built-in buffer worth planning for.
Students Paying Their Own College Expenses
Students covering costs without family support benefit most from prioritizing needs before wants. Work-study programs, flexible part-time jobs, and even small scholarships add up significantly across four years.
How to Handle Financial Aid, Scholarships, and Student Loans in Your Budget
Money from aid and loans needs the same planning as a paycheck, and often more, since it tends to arrive in large, infrequent amounts.
Budgeting Scholarship and Grant Money
Scholarships and grants don’t require repayment, which makes them tempting to spend quickly. Dividing this money across every month it needs to cover, instead of spending it right after it arrives, prevents a cash shortage later in the term.
Managing Financial-Aid Refunds
A financial-aid refund funds an entire semester of living costs, not just the weeks right after it lands in your account. Dividing the total by the number of months it needs to last, then moving that amount into a separate account, keeps spending on pace.
Understanding Work-Study Income
Work-study earnings usually arrive as a regular paycheck, which makes them easier to budget than a lump sum. Federal work-study awards also cap total hours, so this income shouldn’t factor into a budget beyond what the award actually allows.
Borrowing Only What You Need
Accepting a full loan offer feels convenient, but borrowing only the amount needed for that semester keeps future student loan debt lower. Every extra dollar borrowed today comes back later with interest attached.
Keeping Track of Student Loan Obligations
Tracking total borrowed amounts each year, even before payments start, builds a clear picture of a future monthly payment. Most loan servicers offer free calculators that estimate this payment based on the current balance and interest rate.
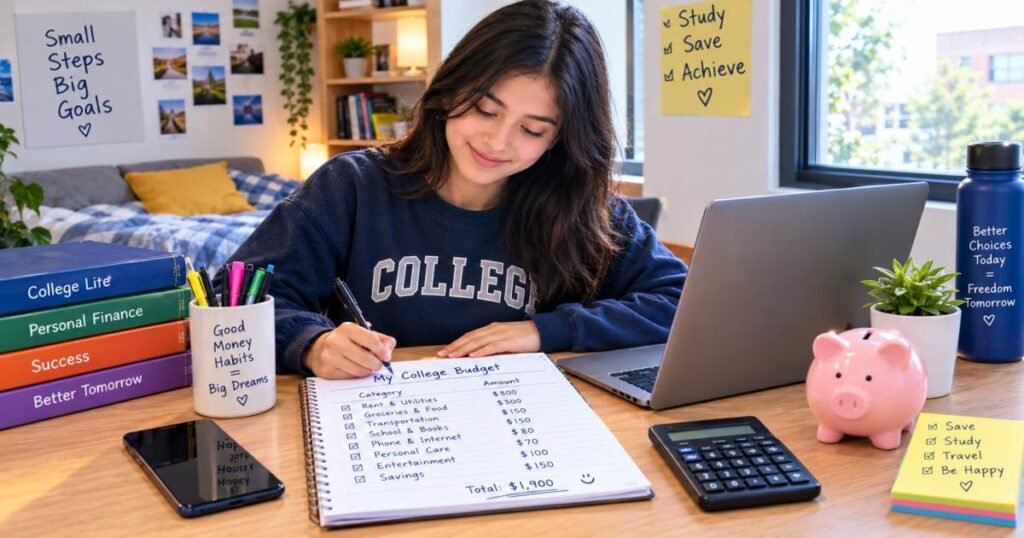
A Simple Monthly College Student Budget Example
Here’s a sample budget for an off-campus student earning $1,600 a month from a part-time job and financial aid:
| Category | Amount |
| Rent (shared apartment) | $600 |
| Groceries | $250 |
| Utilities & internet | $100 |
| Phone plan | $40 |
| Transportation | $100 |
| Textbooks & supplies (monthly average) | $80 |
| Personal care | $50 |
| Entertainment & social | $150 |
| Subscriptions | $30 |
| Savings & emergency fund | $200 |
| Total | $1,600 |
Actual numbers shift by location and lifestyle, but this example shows how every dollar gets a specific job before it’s spent.
Common College Budgeting Mistakes to Avoid
Even careful students fall into these patterns:
- Forgetting irregular costs like semester textbooks or annual subscription renewals
- Skipping small purchases when tracking spending, even though these drain a budget faster than large ones
- Leaving out an emergency fund entirely, with no cushion for surprises
- Covering shortfalls with credit cards instead of adjusting spending
- Building a budget once and never revisiting it as costs change
- Comparing spending to friends instead of building a plan around personal income
Spotting these patterns early makes correcting course far easier than fixing a budget that’s already broken.
Best Tools for Managing a College Budget
A budget works best with a system you’ll actually use consistently.
Budgeting Apps
Apps like YNAB and EveryDollar link directly to bank accounts and categorize spending automatically. These suit students who prefer a visual, hands-off way to track money.
Bank Budgeting Tools
Many banks now build spending trackers and category breakdowns directly into their apps. Students who already use these features rarely need a separate budgeting app on top.
Spreadsheet Templates
A Google Sheets or Excel template gives full control over categories, formulas, and layout. This option suits students who want to customize every detail of their budget.
Simple Cash-Envelope or Spending-Account Systems
Some students prefer a low-tech method: withdrawing cash for variable categories like food and entertainment, then stopping once the envelope runs empty. A digital version works the same way, moving each category’s budget into a separate spending account at the start of the month.
How to Save Money Without Giving Up Your College Experience
Saving money in college doesn’t require saying no to everything enjoyable. It requires deciding, in advance, where money goes.
Pick a few experiences that matter most a trip with friends, a concert, a club membership and budget for those specifically. Then cut spending in areas that matter less personally, like daily coffee runs or subscriptions rarely used.
This targeted approach protects the parts of college that make it worthwhile, because the cuts come from low-value spending rather than everything at once.
What to Do If Your College Budget Is Not Enough
A few options help before a tight budget becomes a real crisis:
- Contact the financial aid office;e additional grants or emergency funds sometimes exist outside the standard aid package
- Check for a campus food pantry or hardship fund, both of which many schools offer quietly
- Pick up additional work-study or part-time hours where your schedule allows
- Reconsider the living situation, such as adding a roommate or moving somewhere more affordable
- Talk with a financial aid counselor before taking on more loans, to understand the long-term cost of borrowing
Acting early gives far more options than waiting until money runs out completely.
Final Thoughts
The most effective college budget isn’t the most detailed one; it’s the one that actually gets followed. Start with the basics: track income, list expenses, set spending limits, and check in weekly.
Monthly costs for college students typically range from about $700 to nearly $1,800 depending on housing choice, which is exactly why a personalized budget beats a generic number. The habits covered here tracking spending, planning for irregular costs, and building even a small emergency fund separate a budget that exists on paper from one that actually works.
Financial literacy for students carries well past graduation. Small, consistent choices now typically mean less financial stress later, both during school and after.
FAQs
How much should a college student budget each month?
Monthly costs for college students typically range from about $700 for students living at home to nearly $1,800 for students living on campus. Building a personal budget from actual income and expenses gives a far more accurate number than any national average.
What are the most important college budget categories?
Housing, food, tuition-related costs, and transportation make up the largest and most essential categories. Savings and personal spending complete a full student budget once those are covered.
How can college students save money on a tight budget?
Cooking at home, buying used textbooks, using student discounts, and canceling unused subscriptions free up cash quickly. Small, consistent changes typically add up to more savings than one large cutback.
Is the 50/30/20 budget rule suitable for college students?
It works as a starting point, though many students need to adjust the percentages to fit real expenses. A ratio like 70/20/10 often fits a tighter student budget better than the original formula.
Should college students have an emergency fund?
Even $300 to $500 can prevent one unexpected expense from turning into a financial emergency. Building it gradually, even $20 a month, works better than not starting at all.
How can students budget financial-aid refund money?
Divide the refund by the number of months it needs to cover, then move that portion into a spending account each month. This prevents the common mistake of spending it too quickly after it arrives.
What is the easiest way to track college expenses?
A budgeting app linked to a bank account usually takes the least effort to maintain. Students who prefer more control often do just as well with a spreadsheet updated weekly.
How can students avoid overspending?
Setting a weekly limit for flexible spending and waiting 24 hours before non-essential purchases both cut overspending significantly. Reviewing the budget weekly catches problems early, before they grow.
2 Comments